Blackstone’s $3.1 billion LNG Canada deal keeps Mitsubishi in control
Subscribe to our free newsletter today to keep up to date with the latest energy news.
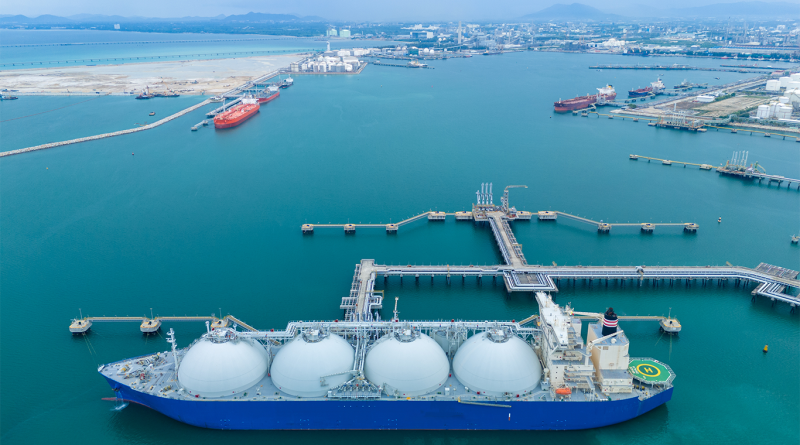
A group led by Blackstone has agreed to invest $3.1 billion in Mitsubishi Corporation’s interest in LNG Canada, bringing private credit and Canadian pension capital into the country’s first large-scale LNG export terminal.
Funds managed by Blackstone Credit & Insurance, together with CPP Investments, OMERS, the Investment Management Corporation of Ontario (IMCO), and PSP Investments, will take a 49.9% non-controlling interest in the Mitsubishi subsidiary that holds its LNG Canada stake. Blackstone announced the deal on Nov. 2.
That subsidiary owns 15% of LNG Canada, the Shell-led export facility in British Columbia that began production in June 2025, Reuters reported. Mitsubishi values its stake at about $1.6 billion, with the remainder of the investment going toward the project’s Phase 2 expansion.
Mitsubishi stays in control. It remains the controlling partner in the holding company and keeps its full share of the LNG it takes from the project.
The deal shows how large LNG partners are finding ways to fund expansion without selling down the cargoes that make the projects strategically valuable to them.
The Blackstone deal separates capital from control
The structure is the most significant part of the transaction for the wider LNG sector.
Rather than selling part of its LNG Canada stake outright, Mitsubishi has brought investors into the holding company that owns it. The investors receive a minority economic interest, while Mitsubishi keeps the management role and the gas.
According to Reuters, the holding company takes 2.1 million metric tons per year of LNG, a volume expected to rise to 4.2 million metric tons once the expansion is complete. Mitsubishi has said the deal will not affect its offtake volumes or its customer relationships.
For a trading house whose business depends on supplying LNG to buyers in Asia, that distinction matters. Mitsubishi gains capital and keeps the contracted supply that underpins those relationships.
The investment also fits Blackstone’s credit business. Blackstone Credit & Insurance led the deal, and Zachary Rubenstein, a managing director in that business, pointed to the firm’s ability to offer “flexible solutions” to large corporations.
Rick Campbell, a senior managing director at Blackstone Credit & Insurance, described Mitsubishi as “a global leader with more than 50 years of experience across the LNG value chain.”
LNG Canada Phase 2 needs capital on a large scale
Phase 2 is what gives the transaction its timing.
Shell and its partners took a final investment decision on the expansion in September 2025. Once complete, Phase 2 will double LNG Canada’s capacity to 28 million metric tons per year, according to Blackstone.
Each partner in the project has to fund its share of that expansion. By bringing in outside investors at the holding company level, Mitsubishi has secured money for its part of Phase 2 without giving up its position in the terminal.
Mitsubishi has said it will use Blackstone’s resources to advance the expansion and improve capital efficiency.
The deal also adds weight to the role of Canadian institutional money in domestic energy infrastructure. The investor group includes 4 Canadian pension and public sector investment managers working alongside Blackstone.
Geoff Souter, managing director and head of real assets credit at CPP Investments, called LNG Canada “a high-quality, globally strategic asset” and described the deal as a chance to invest at scale in Canada.
Pension capital is moving closer to LNG infrastructure
The investment points to a broader shift in who funds LNG.
LNG export projects have long been built around equity from energy majors, national oil companies, and trading houses. This deal brings a credit fund and pension investors into the ownership chain of a project that is still expanding.
The investors are funding a minority stake in a holding company with a large expansion program ahead of it, while the industrial partner keeps control and the commercial relationships.
That model could suit both sides. Long-term investors gain exposure to an export terminal with contracted volumes, and LNG partners gain capital without giving up the supply they have built their businesses around.
It also offers a template other partners in large LNG projects could follow as they face the cost of expansion phases.
Some details have not been disclosed, including the closing conditions. A Mitsubishi spokesperson told Reuters the deal is expected to close in November 2026. The bigger test lies further ahead, in whether Phase 2 is delivered on schedule and whether more LNG partners turn to private credit to fund growth rather than selling stakes outright.
Source
Blackstone