Why crude exports are recovering faster than diesel supplies
Subscribe to our free newsletter today to keep up to date with the latest energy, oil and gas news.
Crude oil is moving out of the Gulf at rates approaching those seen before the Iran conflict, but the recovery conceals a far more uneven picture for companies that depend on refined fuels, predictable freight costs and stable industrial supply chains.
At least 16.5 million barrels a day of crude left the region in September, roughly matching the prewar average when Iranian exports are excluded and marking a substantial rebound from March, when regional crude exports averaged about 6 million barrels a day.
That recovery does not mean the Strait of Hormuz has returned to normal operating conditions, because exporters have restored flows by relying more heavily on pipelines, shuttle tankers and ship-to-ship transfers that reduce dependence on the strait while adding cost, coordination and operational complexity.
For industrial buyers, trucking companies and manufacturers, the more immediate concern sits further downstream, where refined fuels, particularly diesel, have failed to recover at the same pace as crude oil.
A seven-day average of about 677,000 barrels a day of refined products was moving through Hormuz at the end of September, compared with 3.6 million barrels a day before the conflict, which shows why headline crude export figures provide only a partial view of the region’s energy supply chain.
Gulf exporters have rebuilt crude flows around a disrupted chokepoint
The response to the Hormuz disruption has developed into a large-scale logistics exercise in which producers, national oil companies and shipping operators have had to reconstruct export routes rather than wait for traditional trade patterns to return.
Before the conflict, most Gulf crude moved through established maritime corridors in the Strait of Hormuz, with only about 17% of regional crude avoiding the passage, whereas that share has now risen to roughly 40% as Saudi Arabia and the United Arab Emirates make greater use of pipelines and alternative loading points.
Saudi Arabia’s East-West Pipeline gives the kingdom access to the Red Sea at Yanbu and allows some crude to bypass Hormuz entirely, and although the route suffered disruption during the conflict, its return to service has provided exporters with additional capacity outside the Gulf.
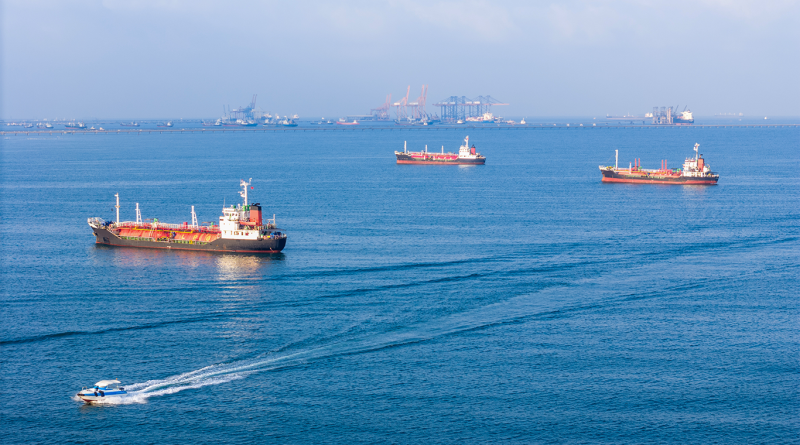
The maritime network has changed just as significantly, with very large crude carriers increasingly operating shuttle services through the strait before delivering cargoes to transfer points outside the most constrained section of the route.
Those cargoes can then be moved onto different vessels off Oman or Fujairah before continuing toward international markets, creating a layered transport system that spreads risk across several legs rather than depending on a single voyage through the strait.
More than 70% of crude that crossed Hormuz in August subsequently changed tankers, according to Kpler data reported by The Guardian, marking a sharp departure from prewar conditions when ship-to-ship transfers of Gulf crude in the Gulf of Oman were uncommon.
The system has continued to evolve as congestion has increased around transfer points, with Lloyd’s List Intelligence identifying 13 former Hormuz shuttle tankers that either delivered Saudi crude directly to India or conducted transfers near India’s west coast during September.
These changes matter beyond the oil sector because they show how a supply network can maintain substantial throughput after losing reliable access to a critical route, provided operators have enough infrastructure, vessels, alternative corridors and capital to build a workable replacement system.
The trade-off is that every additional transfer, voyage and handling operation introduces another point where delays, vessel shortages, security costs or scheduling problems can enter the chain, which means restored throughput should not be mistaken for restored efficiency.
Diesel shows why recovering crude volumes do not mean supply has normalized
The distinction between crude oil and refined products has become increasingly important because a recovery in upstream commodity flows does not automatically translate into a recovery in the finished fuels that power freight, aviation, agriculture, construction and industrial operations.
Crude oil is only the raw material, while diesel, gasoline, jet fuel and other petroleum products require refining capacity, storage, transport and distribution before they can reach commercial users, which means each stage can become a separate bottleneck during a prolonged disruption.
Less than 20% of prewar volumes of refined products were moving through Hormuz at the end of September, according to Kpler data cited by The Guardian, leaving a large gap between the recovery in crude exports and the availability of finished fuels.
The effects have been visible in fuel markets, where diesel has faced particular pressure from constrained Middle Eastern product flows and uncertainty across other parts of the global refining system, with UK diesel prices reaching a record average of 199.18 pence a liter in late September, according to figures reported by The Guardian.
For freight operators, higher diesel prices feed directly into transport costs, while manufacturers can experience the same pressure through inbound freight, outbound distribution and the operating costs of diesel-powered machinery and equipment.
Agricultural businesses, construction companies and other fuel-intensive sectors face a similar exposure because they depend on refined products rather than crude oil itself, making the downstream shortage more commercially relevant than headline production figures.
Energy markets have already shown how quickly disruptions around Hormuz can affect global pricing, with the US Energy Information Administration reporting that Brent crude traded as high as $118 a barrel in late April during the second-quarter disruption before falling to $72 by late June as market conditions shifted.
The gap between crude and refined products reinforces a broader point about energy security because adequate crude production does not protect a market from shortages when refining capacity, shipping availability or product distribution remain constrained.
In a prolonged disruption, those downstream constraints can become more significant to businesses than the availability of raw oil because the economic effect is felt through the fuels, transport services and industrial inputs that companies actually purchase.
Supply chain resilience is being purchased with greater cost and complexity
The revised Gulf transport system functions because companies and governments have been willing to allocate vessels, infrastructure and capital to keep oil moving, but maintaining those flows requires a supply network that is more complicated than the one it replaced.
Ship-to-ship transfers consume additional tanker capacity and require careful coordination, while congestion at transfer points can reduce vessel availability elsewhere and longer voyages can absorb more vessel days across the fleet.
Security risks add another layer of expense because crewing, insurance, operating procedures and routing decisions can all become more costly when vessels are moving through or near areas exposed to military or geopolitical disruption.
Recent tanker market conditions illustrate how quickly those pressures can accumulate, with Lloyd’s List reporting in mid-September that very large crude carrier rates on the Middle East Gulf-to-China route had reached about $1.1 million a day amid disruptions to Saudi export routes and continued tightness in tanker availability.
The US Energy Information Administration has also cautioned that constraints on Hormuz traffic were likely to continue through the fourth quarter of 2026, even as alternative export routes supported a recovery in regional oil production.
For supply chain executives, the distinction between resilience and efficiency is especially important because a network can remain operational under stress while becoming materially more expensive to manage.
A resilient network can continue supplying customers when its preferred route fails, whereas an efficient network is designed to move the same goods with the lowest practical use of capital, inventory and transport capacity, and those two objectives can diverge sharply during a severe disruption.
The Gulf oil trade now provides a large-scale example of that divergence because export volumes have recovered even as the logistics system supporting them has become more capital-intensive, more operationally demanding and more dependent on alternative routing.
The same lesson applies well beyond energy, particularly for manufacturers that have traditionally designed supply chains around stable transport corridors, concentrated suppliers and predictable lead times because those structures reduce costs during normal operating conditions.
When a critical corridor fails, maintaining output may require secondary routes, larger inventories, alternative suppliers and greater control over logistics assets, all of which can appear inefficient during stable periods but become decisive when continuity is threatened.
The recovery in Gulf crude exports should therefore not be interpreted as evidence that the Hormuz problem has disappeared, because it instead shows how logistics networks can absorb severe disruption when operators have access to enough alternative infrastructure, transport capacity and financial resources.
Diesel presents the other side of the same issue, since a supply chain can restore one part of a commodity flow while bottlenecks persist elsewhere and continue to create costs for industrial users.
For manufacturers, freight operators and other industrial businesses, resilience should therefore be measured not only by whether supply continues, but by the amount of capital, transport capacity and operational complexity required to keep that supply moving when the primary route is no longer dependable.
Source:
The Guardian